A Day in the Life of a Florida Claims Adjuster: Storm Season vs. the Off-Season
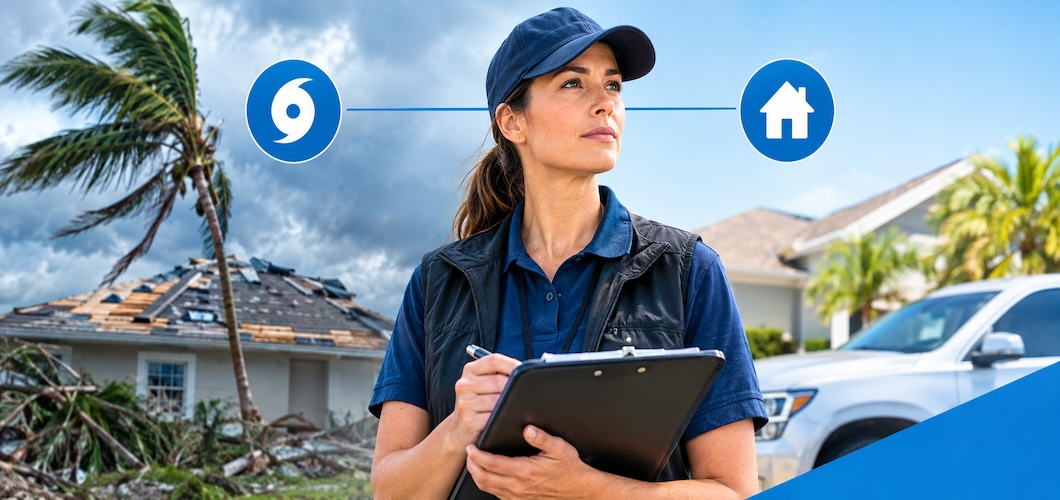
When people think about working as an insurance claims adjuster in Florida, they may picture a vehicle, a clipboard, and a house damaged by a hurricane. Storms are certainly an important part of the Florida insurance industry, but they are only one part of an adjuster's job.
A Florida 6-20 All-Lines Adjuster can work with a wide variety of insurance claims, including property, homeowners, auto, and other covered losses depending on the assignment and employer. The daily routine can change dramatically when a major storm hits the state.
So, what does a Florida claims adjuster actually do all day?
It depends on the season, the type of claims being handled, and whether the adjuster is working for an insurance company, an independent adjusting firm, or on a catastrophe assignment. Here's a closer look at what the job can look like during Florida's busy storm season and what happens when things return to normal.
What Does a Florida 6-20 Claims Adjuster Do?
A claims adjuster's primary responsibility is to investigate insurance claims and gather the information needed to help determine how a claim should be handled under the applicable policy.
That can involve much more than simply looking at damaged property.
- Reviewing claim information and insurance policies
- Contacting policyholders, witnesses, contractors, and other involved parties
- Inspecting damaged property
- Taking photographs and measurements
- Documenting the cause and extent of damage
- Preparing estimates and claim reports
- Reviewing repair documentation and supporting evidence
- Communicating claim information to the appropriate parties
- Following company procedures and applicable insurance regulations
- Updating claim files as new information becomes available
The specific duties vary based on the type of adjuster, employer, claim, and assignment. However, strong investigation, documentation, communication, organization, and attention-to-detail skills are important in virtually every claims environment.
A Typical Day During Florida's Off-Season
The off-season does not mean insurance claims stop. Homes experience plumbing leaks, fires, roof damage, theft, water losses, automobile accidents, and other insured events throughout the year.
For an adjuster working regular daily claims, a typical day may involve several different types of assignments.
8:00 AM: Review the Day's Claims
The day may begin by reviewing new assignments, checking claim files, responding to messages, and planning inspections.
An adjuster might have several claims at different stages. One could require an initial inspection, another might need additional documentation, and a third could be waiting on information from a contractor or policyholder.
Organization becomes critical when multiple claims are moving simultaneously.
9:00 AM: Contact Policyholders
Communication is a major part of claims work.
An adjuster may call a policyholder to discuss the reported loss, gather additional information, explain what will happen next, or schedule an inspection.
For someone considering an insurance adjusting career, this is an important point to understand: claims adjusting is not simply an inspection job. Much of the work involves people, documentation, analysis, and communication.
10:00 AM: Inspect a Property
Depending on the claim, the adjuster may travel to a home, business, vehicle location, or other site to investigate the reported damage.
During a property inspection, the adjuster may document affected areas, take photographs, record measurements, identify visible damage, and gather information about what happened.
The goal is to create an accurate record of the loss.
12:00 PM: Document and Organize the Claim
After an inspection, the work continues.
Photographs, measurements, notes, estimates, statements, invoices, and other documentation may need to be organized and entered into the claim file.
Accurate documentation is one of the most important parts of the job because the claim file needs to clearly reflect the information gathered during the investigation.
2:00 PM: Research and Estimate
Depending on the claim, an adjuster may review repair costs, estimates, photographs, policy information, prior claim information, and other relevant documentation.
Property claims can require particularly detailed work. A seemingly simple roof or water-damage claim can involve multiple areas of a home and a substantial amount of supporting documentation.
4:00 PM: Follow Up and Complete Reports
The afternoon may involve follow-up calls, additional research, communication with contractors or policyholders, and completing claim documentation.
Some claims can be resolved relatively quickly. Others require additional inspections, records, estimates, expert opinions, or communication before the investigation is complete.
What Changes During Florida's Storm Season?
When a major hurricane or tropical storm affects Florida, the pace of claims work can change almost overnight.
A catastrophe can generate thousands of claims across a relatively short period. Adjusters may suddenly be assigned to areas experiencing widespread property damage.
For some adjusters, this means temporarily leaving their normal routine and traveling to a disaster area.
More Claims, More Travel, More Pressure
During a significant catastrophe, an adjuster's schedule may become much more inspection-heavy.
Instead of handling a few unrelated claims spread across a normal service area, an adjuster may spend days traveling between damaged properties in an area affected by the storm.
Depending on the assignment, the workday may begin early and involve multiple property inspections before the adjuster returns to complete documentation and reports.
Inspecting Storm Damage
Hurricanes and severe storms can create a wide range of losses, including:
- Roof damage
- Wind damage
- Water intrusion
- Flood-related issues
- Tree and debris damage
- Structural damage
- Damage to personal property
- Vehicle damage
- Damage caused by fallen trees or other objects
The adjuster's job is to carefully document what is visible and gather information relevant to the claim.
Storm damage investigations can be particularly challenging because multiple causes of damage may exist at the same property. Understanding the applicable policy and accurately documenting the facts becomes especially important.
A Storm-Season Adjuster's Day May Start Early
During a major catastrophe, an adjuster's schedule may look very different from a normal off-season day.
A day could involve:
- Reviewing a list of assigned claims
- Driving to multiple properties
- Inspecting roofs and exterior damage
- Photographing damaged areas
- Speaking with homeowners
- Recording measurements and observations
- Reviewing contractor estimates
- Preparing claim reports
- Updating claim files
- Preparing for the next day's assignments
In a widespread catastrophe, adjusters may work extended schedules for periods of time because insurers and policyholders need claims investigated and documented as efficiently as possible.
Why Documentation Matters Even More After a Storm
After a major storm, there can be enormous pressure to move quickly. However, speed does not replace accuracy.
An adjuster may be responsible for documenting hundreds of details across multiple claims. Photographs need to be organized. Measurements need to be accurate. Statements need to be recorded properly. Estimates need to correspond with the observed damage.
The ability to stay organized while working quickly is therefore an important skill for catastrophe claims adjusting.
What Happens After the Storm?
Storm-related claims do not disappear when the skies clear.
In fact, the weeks and months following a major hurricane can remain extremely busy.
Policyholders may discover additional damage, contractors may submit estimates, supplemental information may arrive, and previously inspected claims may require additional review.
Adjusters may return for supplemental inspections or continue working through existing claim files.
This means storm-season work can extend well beyond the actual weather event.
Is Florida Claims Adjusting a Desk Job or a Field Job?
It can be either or both.
Some adjusters spend much of their time in the field inspecting losses. Others perform more desk-based claims work involving documentation, phone calls, estimates, policy review, and file management.
Many adjusting careers combine the two.
This variety is one reason the profession can appeal to people with different backgrounds. Someone who enjoys working with people and being out in the field may prefer inspection-heavy assignments, while someone who enjoys analysis, documentation, and organization may prefer desk-oriented claims work.
What Skills Make a Good Claims Adjuster?
A Florida claims adjusting career requires more than knowing insurance terminology. Successful adjusters often rely on a combination of technical and interpersonal skills.
Attention to Detail
Claims can involve numerous facts, documents, photographs, measurements, estimates, and policy provisions. Small details can matter.
Communication
Adjusters regularly communicate with policyholders, contractors, repair professionals, supervisors, and other parties involved in a claim.
Organization
Keeping multiple claims organized is essential, particularly during catastrophe assignments when the volume of work can increase dramatically.
Problem Solving
Every claim is different. Adjusters need to gather information, evaluate what they find, and determine what additional information may be needed to complete the investigation.
Technology Skills
Modern claims adjusting involves digital photographs, estimating software, electronic claim files, mobile applications, communication platforms, and other technology.
Professionalism
Policyholders may be dealing with significant property damage and disruption. Clear, professional communication is an important part of the claims process.
Can a Florida 6-20 Adjuster Work During Storm Season and Off-Season?
Yes. One of the potential advantages of an adjusting career is that claims exist throughout the year.
The type and volume of work can change depending on weather, geography, employer, and the adjuster's assignments.
Some adjusters work primarily on everyday claims. Others pursue catastrophe assignments when major storms occur. Independent adjusters may have opportunities to work in different locations depending on available assignments.
For someone interested in a career with seasonal changes, the combination of routine claims work and catastrophe assignments can provide a different experience throughout the year.
How Do You Become a Florida 6-20 All-Lines Adjuster?
The Florida 6-20 All-Lines Adjuster license is an important credential for people interested in pursuing insurance claims adjusting in Florida.
The licensing process involves meeting Florida's applicable licensing requirements and completing the required education or examination pathway. Requirements can change, so prospective adjusters should always verify current requirements with the Florida Department of Financial Services before beginning the licensing process.
For people considering this career path, completing a Florida-approved adjuster course can help build the insurance knowledge needed to understand policies, claims terminology, and the fundamentals of adjusting.
Is Claims Adjusting a Good Career for Someone Changing Careers?
Claims adjusting can be an option worth exploring for people coming from a variety of professional backgrounds.
Experience in customer service, construction, property management, automotive work, administration, sales, or other fields may provide transferable skills that can be useful in claims.
For example, someone with customer service experience may already be comfortable communicating with people during stressful situations. Someone with construction experience may understand building materials and repair processes. An administrative professional may already have strong documentation and organizational skills.
A license does not guarantee employment, but obtaining the appropriate insurance credential can provide a foundation for pursuing claims-related opportunities.
Storm Season vs. Off-Season: What's the Difference?
| Storm Season | Off-Season |
|---|---|
| Potentially high claim volume | More predictable claim volume |
| Catastrophe assignments may become available | Everyday claims remain active |
| More travel may be required | Assignments may remain within a regular service area |
| Multiple inspections may occur each day | Greater variety of claim types and schedules |
| Longer or more demanding work periods may occur | More routine scheduling may be possible |
| Storm-related property damage is a major focus | Claims may include water, fire, auto, theft, liability, and other losses |
There is no single schedule that applies to every Florida adjuster. Employment arrangements, claim volume, geographic location, employer, and individual assignments can all affect the day-to-day experience.
The Bottom Line: What Does a Florida Claims Adjuster Really Do?
A Florida claims adjuster's job is ultimately about investigating, documenting, and helping process insurance claims.
During the off-season, that may mean inspecting individual losses, reviewing documentation, communicating with policyholders, preparing estimates, and managing claim files.
During storm season, the pace can change dramatically. A major hurricane can create a surge of claims, increase travel requirements, and create opportunities for catastrophe assignments.
But whether the weather is calm or a major storm has just passed, the fundamentals remain the same: investigate carefully, document accurately, communicate professionally, and understand the insurance policy and applicable requirements.
Ready to Explore a Florida Adjusting Career?
If the idea of combining insurance knowledge, investigation, field work, technology, and problem solving sounds interesting, becoming a Florida claims adjuster may be worth exploring.
OnLine Training provides online insurance education designed to help Florida students prepare for their licensing goals on a schedule that works for them.
Start Your Florida Adjuster Career Today
Enroll in OLT's Florida approved INS013FL40 Accredited Claims Adjuster Course and take the next step toward earning your Florida 6-20 All-Lines Adjuster License.
Explore Florida Adjuster Courses